Water Backup vs. Flood Insurance: A Guide for Texas and Ohio Homeowners
A burst pipe, backed-up drain, and rising floodwater may need different coverage. Learn what to check before water reaches your Texas or Ohio home.
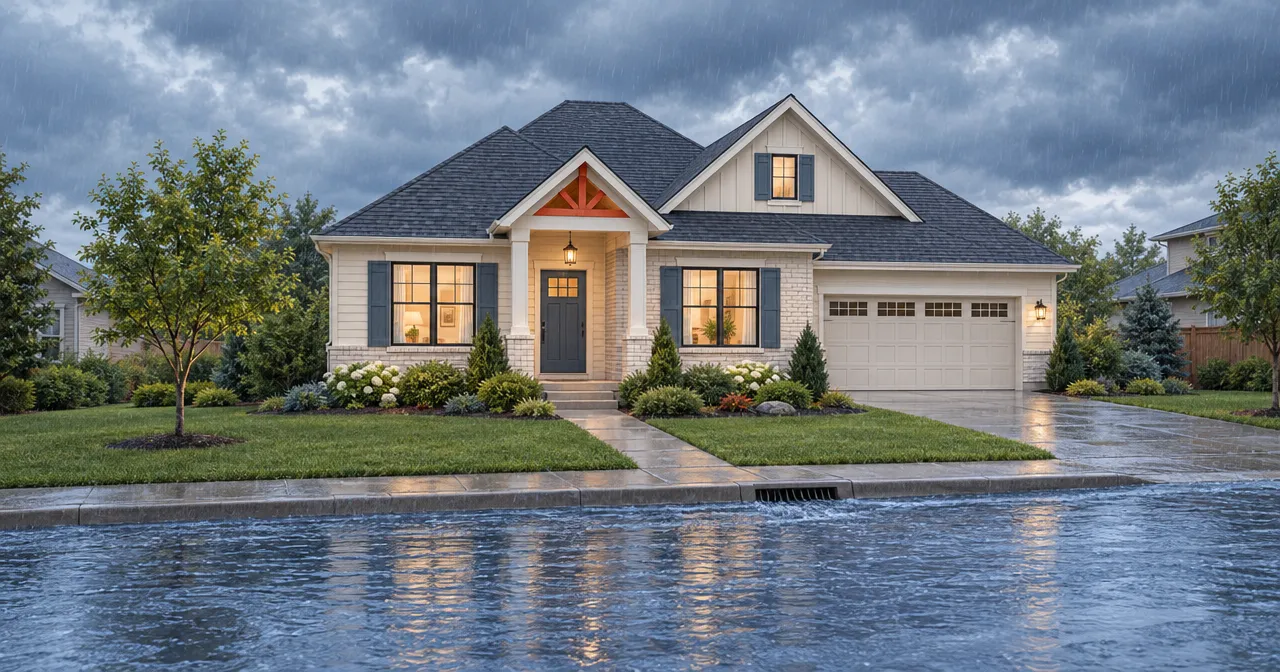
A puddle on the laundry-room floor and water moving across a front yard are both “water damage” in everyday speech. To an insurer, they may be entirely different losses. The source of the water, the route it took into the house, and the wording of your policies determine which coverage—if any—can respond.
That distinction matters for a homeowner in San Antonio watching rain collect at the curb, a family in Austin with a backed-up floor drain, or someone in Cincinnati with a finished basement and a sump pump. A homeowners policy, a water backup endorsement, and a flood policy are not interchangeable. Here is a practical way to separate them and review the limits before you need to file a claim.
Start with the path the water took
Think about three different events:
- Water escapes from a pipe or appliance inside the house. A supply line suddenly breaks behind a washing machine and soaks the floor. This is generally a question for the homeowners policy’s sudden-and-accidental water provisions, subject to its exclusions and deductible.
- Water comes back up through a drain or sewer—or a sump pump fails. A basement floor drain overflows after a blockage, or a sump stops moving water. This is the problem a water backup or sump-overflow endorsement may address, if purchased and if the precise cause falls within its terms.
- Water moves over normally dry ground and enters from outside. Heavy rain creates surface runoff that crosses the threshold, or a creek overflows. This is generally a flood-insurance question, not an ordinary homeowners or water-backup claim.
These examples describe likely starting points, not claim decisions. A storm can cause more than one type of loss at the same property, and the fact that it rained does not by itself turn every basement loss into a covered flood. The Texas Department of Insurance home insurance guide notes that most Texas policies cover a sudden, accidental release of water but not flooding or continuous leakage; it also lists sewer/drain backup among common add-on coverages. Your own contract is the deciding document.
What a homeowners policy may cover—and what it may not
For a sudden pipe break, a homeowners policy may pay for resulting damage to covered floors, walls, and belongings. That does not necessarily mean it will pay to replace the failed pipe or appliance itself. Wear and tear, an ongoing leak, maintenance issues, or loss during a prolonged vacancy can be treated differently from a sudden accident. Find out what caused the damage and read the policy’s exclusions before assuming the entire repair is covered.
It also helps to separate the coverage trigger from the payment amount. A $25,000 covered repair is not a $25,000 check if your deductible applies, a category has a special limit, or damaged belongings are valued at actual cash value rather than replacement cost. Actual cash value accounts for depreciation; replacement-cost terms generally pay based on the cost of a comparable repair or replacement, subject to the policy’s conditions. The National Association of Insurance Commissioners’ homeowners guide explains these distinctions and recommends reviewing a policy as circumstances change.
Consider two nearly identical-looking wet walls. A pipe that ruptured overnight is one scenario; a concealed fitting that slowly seeped for months is another. Take photos and arrange for a qualified professional to identify the source. Do not describe the cause as “a burst pipe” if nobody has yet established that it burst.
Water backup coverage is an endorsement, not a flood substitute
A water backup endorsement may add protection when water or sewage backs up through a sewer or drain. Some versions also address sump-pump failure or overflow. Do not assume a sump pump is included simply because a quote says “water backup.” Ask for the endorsement text and verify its definition of a backup, the sump-pump language, any maintenance or power-failure conditions, and exclusions.
Look at the endorsement’s separate limit and deductible. A homeowner might have a high dwelling limit but only a $10,000 water-backup limit. If an otherwise eligible backup causes $15,000 of damage, the $10,000 cap can leave at least $5,000 unpaid even before you account for other policy terms. That example is arithmetic, not a prediction of how a particular insurer will settle a claim. Ask whether cleanup, damaged building materials, and personal property all share one limit, and whether finished-basement improvements count toward it.
Water backup is not a catch-all for water below ground level. Water seeping through a foundation, groundwater entering a basement, and surface water flowing through a door can be excluded even when they end up on the same floor as a backed-up drain. A plumber’s findings about where the water came from can matter as much as the rain report. In Texas, the TDI guide describes sewer/drain backup as an optional endorsement; in Ohio, the same practical step applies: read your policy and ask your agent what the actual form covers rather than relying on a generic label.
For a Cincinnati house with a finished lower level, inventory the flooring, drywall, furniture, and equipment near the sump or floor drain. For a San Antonio or New Braunfels home without a basement, check whether ground-level plumbing and drains present similar exposure. The right limit depends on what is actually at risk, not on a standard number copied from another house.
Flood insurance addresses water from outside
Most homeowners policies exclude flood damage. The National Flood Insurance Program (NFIP) describes a flood, under its policy definition, as inundation of two or more acres of normally dry land or two or more properties caused by events such as overflowing waters or unusual, rapid surface-water runoff. A street-to-garage flow during a downpour may warrant a flood review even if the home is not beside a river. See the NFIP’s explanation of what counts as a flood.
The NFIP offers building and contents coverage, usually purchased separately and with separate deductibles. For a residential homeowner, NFIP limits are up to $250,000 for the building and $100,000 for contents. That building limit can be lower than a home’s replacement cost, so check whether the available limits fit the property and ask about private-flood options when appropriate. A private policy may differ in triggers, limits, exclusions, waiting periods, and claims procedures; compare the actual forms, not just the headline premium.
Basements deserve close attention. NFIP coverage is limited there: essential building systems may qualify under its rules, but personal property kept in basements is not covered under the standard policy. NFIP flood insurance also excludes temporary housing and additional living expenses. Its coverage and purchasing guide sets out those limits and says NFIP coverage generally begins 30 days after purchase, with specified exceptions, including some mortgage-related transactions. A policy bought when water is already approaching is not a reliable solution.
A lender’s requirement is not a complete risk assessment. FEMA explains that flood risk remains outside high-risk map zones and provides guidance on flood-zone risk. Ask about local drainage, nearby creeks, the slope toward the house, and prior water incidents in addition to checking the map. This applies to homes in El Paso, Boerne, Helotes, Leon Valley, and elsewhere just as it does to properties near larger waterways.
When a drain backs up during a flood
This is the gray area that deserves a careful conversation, not a slogan. A clogged sewer line can send water out of a floor drain on a clear day; that may point to a water-backup endorsement, not flood insurance. But a flood can also force water through a sewer. The NFIP explains that its policy may cover sewer-backup damage when the backup was caused by a covered flood, while a backup from clogged pipes would not qualify on that basis. The flood must meet the policy’s definition and the insured property and damage must satisfy the policy terms.
If a storm brings surface water through a doorway and a drain overflows, document both routes separately. One event does not guarantee one policy will pay for all damage. Ask the insurers or your agent how they want the losses reported, preserve photographs of outside water levels and the drain, and avoid guessing at a single cause. A contractor’s or plumber’s written observations can help establish the sequence. Water-backup and flood coverage work best as a coordinated review, not as two presumed payments for the same item.
A six-point review before you buy or renew
1. Find the declarations and forms, not just the premium. Mark your dwelling and belongings limits, the water-backup endorsement (if any), flood building and contents limits, and each deductible. A homeowners deductible and a flood deductible are not necessarily the same; NFIP building and contents deductibles are separate.
2. Describe the house accurately. Tell your agent about a finished basement, floor drains, sump pump, ground-floor appliances, below-grade storage, and any history of water entering the home. If you are buying a house, request the policy review before closing so you can address waiting periods and lender requirements.
3. Ask how the endorsement defines a loss. Does it include sewer/drain backup, sump overflow, or both? Does the limit apply once per occurrence? Are cleanup and damaged contents included within that limit? What happens if the pump stops during a power outage? Get the insurer’s wording rather than treating a quote summary as a promise.
4. Compare values as well as limits. Check whether damaged building finishes and personal property settle on replacement-cost or actual-cash-value terms. Review any sublimits for valuables or categories of property. A higher headline limit does not erase depreciation, exclusions, or a separate backup cap.
5. Review flood coverage independently. Confirm that you have selected both building and contents coverage if you need both. Ask what the policy does with below-grade spaces, temporary lodging, and detached property. If you are considering a private policy, compare the effective date and exclusions with the NFIP option.
6. Revisit the review after a change. A remodeled lower level, a new home office, a newly purchased rental, or a business storing equipment in a basement changes the inventory at risk. A personal policy may not protect business inventory or a rental exposure the same way it protects an owner-occupied home. Discuss those uses with the agent and review the appropriate landlord or business property coverage separately.
For a Texas or Ohio small business, this last point is especially important: the NFIP notes that it does not pay for financial losses from business interruption, even when it covers eligible physical flood damage. Commercial property, flood, and business-interruption provisions need their own coordinated review.
If water enters the house, document the cause safely
First make the space safe: avoid standing water near electrical equipment, shut off a water supply if you can do so safely, and call the appropriate emergency or licensed repair professional. Do not enter moving floodwater. Once safe, photograph the entry points, water line, damaged rooms, and affected belongings before cleanup. Save plumber and mitigation reports, receipts, and a list of damaged items. Notify the insurer promptly, make reasonable temporary steps to prevent further damage, and ask what documentation the adjuster needs before permanent repairs. The TDI guide gives similar claim-documentation advice for Texas homeowners.
You can reduce risk while sorting out coverage: maintain drains, test and service a sump pump where one exists, keep valuable items off a basement floor, and learn how water moves across your property during heavy rain. None of these measures changes an exclusion into coverage, but they may reduce the size of a loss.
Eigel Agency helps homeowners in Texas and Ohio review policies together, spot gaps or overlaps, and discuss coverage in plain language. If you are buying a home or unsure how your current protection treats pipes, drains, and floodwater, request a personalized home-insurance review or contact the team with your policy questions. The useful answer is not “water damage is covered”; it is knowing which water, under which policy, up to what limit.